Construction of the Theoretical Base
Construction of the Theoretical Base
VAT is an indirect tax levied on consumption through the taxation of goods supplied and services provided by businesses or professionals. The mechanism for passing on the tax at each stage of the production and distribution cycle of goods and services to the total value of the transaction, and the possibility of deducting the taxes borne by purchases from the passed-on taxes, guarantees the neutrality of the tax, which, reaching all phases of activity, taxes only the added value generated in each of them. Taxpayers of this tax, i.e., business owners and professionals who carry out taxable transactions, are required to file periodic returns, Form 303, and an annual summary return, Form 390, with the exception of business owners exempt from filing such an annual summary return. The information necessary for the liquidation of the tax and the quantification of certain economic aggregates will be collected from these two sources.
The calculation of individual added values is derived from the data declared in the annual summary declaration, form 390, and from the pseudo-declaration 390 calculated for those taxpayers exempt from the obligation to file an annual summary and for those covered by the SII.
A consumption-type value-added tax, such as the one adopted in the EU, taxes only one component of GDP: domestic consumption. Domestic consumption will therefore be the theoretical concept associated with the Theoretical Basis of the tax, also called Final Expenditure subject to VAT.
With the limitations set out, the magnitudes of the statements are obtained from Total sales, Current purchases and, by difference, the Added Value. The relevant variables of Trade Balance of Goods and Services and a magnitude of the net business investment in fixed assets. As a complement and aid to the analysis, the average sales and purchase rates and the value-added and investment rates in relation to Total Sales are calculated.
Total Sales is the aggregate of Domestic Sales and Foreign Sales, formed, in turn, by the aggregation of Exports and Intra-Community Deliveries.
An additional contribution of the publication is the aggregate calculation of the Theoretical Basis of the Tax or consumption levied based on the declarations. Traditionally, the theoretical tax base is calculated from the perspective of consumption or demand from households, public administrations, and exempt sectors, which are the entities that bear VAT without the possibility of deduction. Thus, the revenue would be obtained as a sum of the tax corresponding to the Final Consumption of Households and Public Administrations and Intermediate Consumption and Gross Fixed Capital Formation of Public Administrations and exempt sectors. In other words, the value of final goods and services consumed by households, administration and exempt sectors would conceptually constitute the Theoretical Basis; in such a way that the collection would be obtained as a product of the same by a weighted average rate that synthetically represents through a single rate, the weighting of the operations at the different rates in force in each case.
In this statistic, the construction of the Theoretical Base is carried out according to the following approach:
From a conceptual point of view, in aggregate terms, the definition of consumption must start from the definition of GDP. This can be addressed from the supply perspective in the terms outlined above:

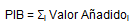
And also from the demand perspective:

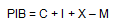
From this perspective, the concepts that make up GDP are defined in aggregate terms. If VAT is levied on consumption, the BIT (Theoretical Tax Base) of the tax could be identified with consumption as follows:

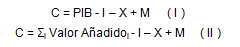
Also being:

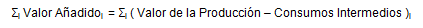
The generic statement contemplated in expression (I) to define consumption must be subject to some qualifications to include the requirements of the VAT regulations and to define the authentic approximation to the BIT of the tax. All necessary details will be discussed in the section describing the "BIT or Final Expense Subject to VAT" delimitation process.
Therefore,

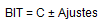
Within the EU, the tax has been settled using a "quota-on-quota" mechanism, with the inclusion of some special regimes authorized for member countries. This means that the information that must be completed when filing the tax is primarily related to the fees. The amount to be paid or refunded, in short, the VAT balance of each subject, is calculated by the differences between the accrued amounts and the deductible amounts.
However, our periodic tax settlement models, and in even more detail the annual summary declaration 390, not only contemplate the information of the quotas but also include the information of the taxable bases, and other relevant variables for informative purposes to know the total volume of operations of each company (including exempt sales and even those not subject to tax) or the total amount of purchases (including those corresponding to input and non-deductible tax, etc.). All this allows the quantification of the "Theoretical Basis" and expressing the collection of the period through the following expression:

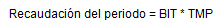
Where TMP is the weighted average rate.
The approximation of the different economic aggregates defined in statistics to the theoretical economic concepts used in National Accounting and, more specifically, to the economic variables presented from the supply perspective, is carried out by defining equivalent or approximate economic magnitudes, constructed from the tax variables provided in their declarations by the companies that make up the country's productive fabric. Logically, the conceptual identity of the fiscal magnitudes and the national accounting magnitudes defined in a precise manner in the ESA 95 (European System of Accounts) is not guaranteed.