Consulting company tax data
The online service for consulting 2025 corporation tax data is intended to assist with the completion of the tax return for the 2025 fiscal year and is exclusively for legal persons, regardless of the type of entity, the tax year, or whether they had submitted a self-assessment for the previous financial year.
Taxpayers whose tax period does not coincide with the calendar year – that is, those filing tax returns of types 2 and 3 – should bear in mind that the information provided relates to the calendar year 2025.
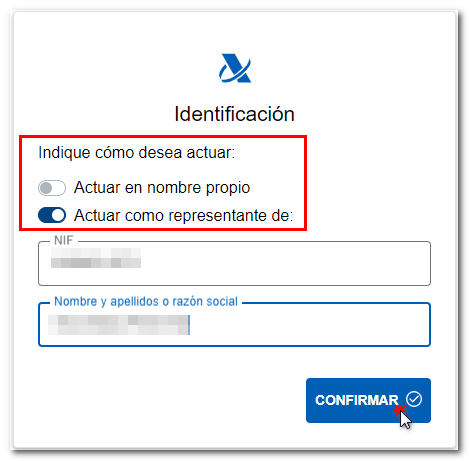
To log in on your own behalf, you need to authenticate yourself using an electronic certificate, an electronic DNI or eIDAS.
This enquiry service only allows access via empowerment (it does NOT allow for socialcollaboration ), and the specific empowerment required is DFIS ( Corporate Tax Data Enquiry) or the general empowerment for personal data consultations, GENERALDATPE.
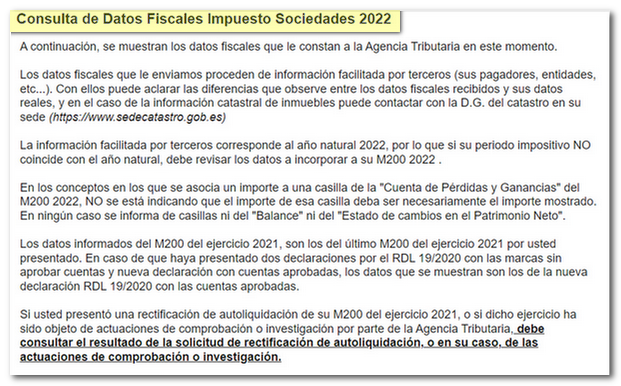
At the top of the page, you can consult further information about the tax data that will be provided through this service.
Below you will find the tax data for the 2025 fiscal year. There is no printable version or download option, as this is an online enquiry. This service only displays information provided by third parties relating to the calendar year 2025. If the tax period does not coincide with the calendar year, you must check the details you need to include on your Form 200 for 2025.
The data provided can be grouped into the following categories:
Data held by the Tax Agency derived from information returns or other sources of information provided by third parties. You can use these to clarify any discrepancies you notice between the tax data you have received and your actual figures; and, in the case of land registry information, you can contact the Directorate-General for the Land Registry at its headquarters (https://www.sedecatastro.gob.es)
Data from self-assessments and information returns submitted by the taxpayer (M202, M190, M390 or M303).
In cases where an amount is associated with a box in the ‘Profit and Loss Account’ section of Form 200 for 2025, this does not necessarily mean that the amount shown in that box must be the amount indicated. Under no circumstances are details provided regarding the ‘Balance Sheet’, the ‘Statement of Changes in Net Worth’ or the ‘Statement of Changes in Net Worth’.
Figures declared on Form 200 for the 2024 tax year relating to amounts to be carried forward to future tax years, indicating the box on Form 200 for the 2025 tax year in which they should be entered. If you have submitted a correction to your self-assessment Form 200 for the 2024 tax year, or if that tax year has been the subject of an audit or investigation by the Tax Agency, you should consult the outcome of the request to amend the self-assessment, or, where applicable, the outcome of the audit or investigation. In addition, the information set out on pages 1 and 2 will be provided.
Information to be included in the tax return, such as details relating to penalties and surcharges imposed and notified by the AEAT (State Tax Administration Agency) during the 2025 tax year, late payment interest paid by the AEAT and other tax authorities during 2025, etc.
Economic activity tax categories under which the taxpayer is registered, including the corresponding National Economic Activity Code (CNAE) .